
PLTR: The AI Stock That’s Rewriting the Rules – A Trader’s Deep Dive
The Numbers Don’t Lie
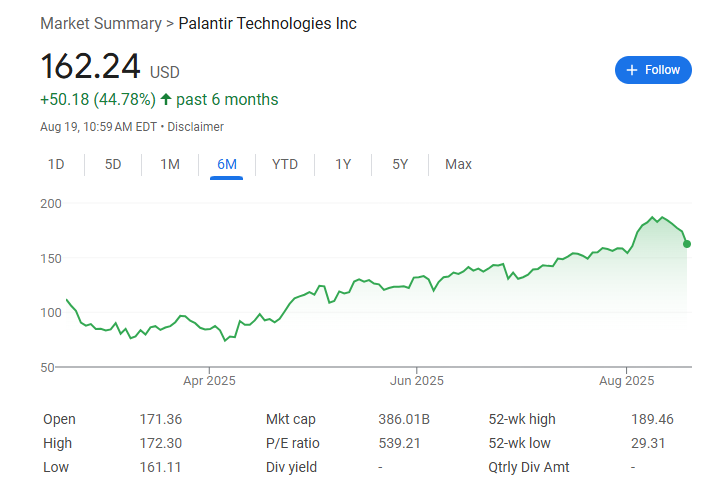
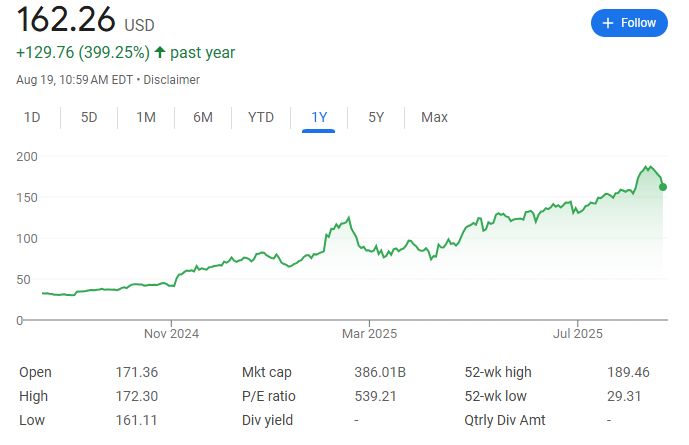
Let’s cut straight to what matters: Palantir (NASDAQ: PLTR) just became the first S&P 500 stock to double two years in a row. We’re talking about a 340% gain in 2024 followed by another 100%+ surge through mid-2025. If you’re a momentum trader, this is the kind of setup that makes careers.
But here’s what really gets my attention – this isn’t just hype. The fundamentals are backing up every dollar of this rally.
Why This Rally Has Legs
The Revenue Acceleration Story
Palantir just crossed the $1 billion quarterly revenue milestone for the first time, posting a 48% year-over-year jump in Q2. What’s even more impressive? They’ve now accelerated revenue growth for eight consecutive quarters. That’s not a fluke – that’s a business hitting its stride.
The real goldmine is their U.S. commercial segment, which exploded 93% to $306 million. Think about what that means for a trader: every quarter, you’re getting confirmation that this growth engine is just getting started.
The Customer Explosion
Here’s a metric that screams “buy the dips” – customer count is up 43% year-over-year, but more importantly, existing customers are spending 28% more (net dollar retention of 128%). When customers are not just staying but dramatically increasing their spending, you’re looking at a platform that’s becoming mission-critical.
The Contract Pipeline That Changes Everything
Remember that $10 billion, 10-year Army contract? That’s not just revenue – that’s predictable cash flow stretching into the next decade. Add in the fact that remaining deal value in the commercial segment more than doubled to $2.79 billion, and you’re looking at a company with unprecedented visibility into future growth.
What Palantir Actually Does (And Why It Matters for Trading)
Forget the complex explanations. Here’s what you need to know: Palantir built the data foundation that makes AI actually useful in the real world. While everyone else is building chatbots, Palantir is building the operating system that lets companies use AI to solve actual business problems.
Their Artificial Intelligence Platform (AIP) isn’t just software – it’s becoming the nervous system for how organizations make decisions. When a hospital uses it to predict sepsis, or an insurance company uses it for underwriting, or a manufacturer optimizes their supply chain, they’re not just using a tool – they’re rewiring how they operate.
This is why customers stick around and spend more. Once you rebuild your operations around Palantir’s platform, switching becomes nearly impossible.
The Trading Reality Check
Let’s be honest about the elephant in the room: this stock is expensive. We’re talking about a forward P/S ratio approaching triple digits and a P/E near 275. Even after a 50% pullback, this wouldn’t be cheap by traditional metrics.
But here’s what I’ve learned after years of trading growth stocks: when you find a company growing revenue at 48% with accelerating momentum, expanding margins, and a moat this wide, traditional valuation metrics become less relevant. The market is pricing in the potential, not the present.
What Could Derail This Train
Every trader needs to know the risks:
- Execution Risk: At these growth rates and valuations, there’s zero room for error. One disappointing quarter could trigger a 30%+ selloff
- International Weakness: Their international commercial segment actually declined slightly last quarter – if they can’t crack global markets, the growth story gets more limited
- Government Spending: While they haven’t felt the impact yet, defense spending cuts could eventually hit their largest customer base
- Competition: Analysts are starting to worry about competitors catching up, which could compress those sky-high margins
The Trading Opportunity
Here’s my take as someone who’s been watching this stock closely: Palantir isn’t just riding the AI wave – they’re creating it. The breadth of use cases for their platform is staggering, and they’re still in the early innings of deployment with most customers.
For momentum traders: This stock has shown an incredible ability to sustain trends. The eight-quarter acceleration in revenue growth gives you a fundamental backstop for technical breakouts.
For swing traders: Watch for pullbacks to key support levels. This stock has violent moves in both directions, but the long-term trend remains your friend.
For position traders: If you can stomach the volatility, this could be one of those once-in-a-decade AI infrastructure plays. The switching costs and network effects are real, and they’re building something that looks increasingly like critical infrastructure for the AI economy.
The Bottom Line
Is PLTR expensive? Absolutely. Could it get cut in half on any disappointment? Without question. But sometimes the market gives you a chance to own a piece of genuine technological disruption while it’s happening.
The company just proved they can hit $1 billion quarterly revenue while accelerating growth. They’re expanding their customer base, increasing wallet share, and building a platform that customers literally can’t live without once they adopt it.
For traders willing to accept the volatility in exchange for exposure to what might be the defining AI infrastructure company of this decade, PLTR deserves serious consideration. Just make sure you’re sizing your position appropriately – this is a rocket ship that could take you to the moon or leave you stranded on the launch pad.
Remember: This analysis is for educational purposes. Always do your own research and never risk more than you can afford to lose. Past performance doesn’t guarantee future results, and high-growth stocks like PLTR can be extremely volatile.